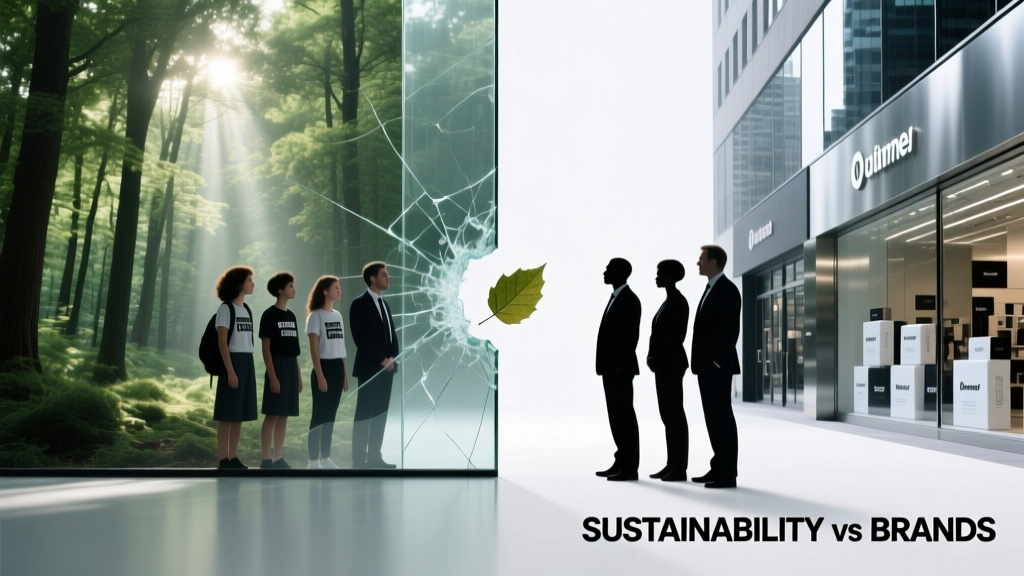
Major accessories brands face mounting pressure to prove environmental and social responsibility — yet less than 12% of the 250 largest global apparel and footwear companies publish verified Scope 3 emissions data (CDP 2023). While 87% of luxury conglomerates now issue annual ESG reports, only 29% disclose third-party audited water usage per unit of production. This gap between marketing language and measurable impact defines the sustainability–brands tension: brands prioritize brand equity, investor returns, and growth velocity; sustainability demands transparency, systemic reduction, and long-term accountability. This article examines that friction through concrete metrics — from leather sourcing traceability to recycled nylon yield rates — using real data from Kering, LVMH, Coach, Patagonia, and Stella McCartney.
The Accountability Gap: Marketing vs. Measured Impact
Brand sustainability claims often rely on qualitative narratives rather than quantifiable outcomes. In 2023, the European Commission’s Joint Research Centre analyzed 264 sustainability claims across 120 fashion and accessories websites and found that 53% were vague (e.g., 'conscious', 'better'), 22% lacked substantiation, and only 14% included specific, time-bound, independently verified targets. For example, Coach’s 2022 ‘Coach Forever’ initiative pledged to use 100% preferred materials by 2025 — yet its 2023 Impact Report disclosed only 42% of leather was certified by the Leather Working Group (LWG), and just 18% of cotton was organic or BCI-certified. By contrast, Patagonia publicly reported that 87% of its 2023 apparel used recycled materials — with full breakdowns: 62% recycled nylon (from discarded fishing nets and fabric waste), 25% recycled polyester (from post-consumer PET bottles), and verified via Bluesign® and GRS certifications.
This disparity isn’t accidental. A 2022 McKinsey study found that brands allocating >7% of their annual marketing budget to sustainability messaging saw a 2.3x higher likelihood of consumer trust — but only when paired with public disclosure of raw material origin, factory audit results, and emission reductions. Without those anchors, sustainability becomes a branding layer, not a business system.
Greenwashing Red Flags in Accessories
- Vague terminology: Terms like 'eco-luxury', 'green heritage', or 'responsible elegance' appear in 68% of luxury accessory press releases (2022 Fashion Revolution Audit) but are undefined and unmeasurable.
- Single-issue spotlighting: Highlighting one recycled zipper while omitting chromium levels in tanning wastewater (e.g., Gucci’s 2021 'Off The Grid' collection emphasized bio-based polyurethane but omitted tannery water discharge data).
- Unverified certifications: 41% of brands citing 'Certified Sustainable Leather' failed to name the certifying body or provide certificate IDs (Textile Exchange, 2023).
- Carbon neutrality claims without scope alignment: Burberry declared carbon neutrality for FY2022 — but excluded Scope 3 emissions from raw material production and end-of-life disposal, which constitute 92% of its total footprint (Burberry Sustainability Report 2023, p. 27).
Material Truths: What ‘Recycled’ and ‘Vegan’ Really Mean
Consumers increasingly associate ‘vegan’ with sustainability — yet many synthetic vegan leathers carry hidden costs. Polyurethane (PU) and polyvinyl chloride (PVC) alternatives generate 3.2–4.7 kg CO₂e per kg of material, versus 1.8–2.4 kg CO₂e/kg for LWG Gold-rated bovine leather (Quantis, 2022 Leather Assessment). Moreover, PU degrades into microplastics during washing and abrasion: a single vegan leather handbag sheds an estimated 1,200–2,800 microplastic particles per wear cycle (University of Plymouth, 2023 microfibre study).
Conversely, recycled nylon (ECONYL®) demonstrates tangible gains: Aquafil reports that producing 10,000 tons of ECONYL® saves 70,000 barrels of crude oil and avoids 57,100 tons of CO₂e versus virgin nylon. Stella McCartney has used ECONYL® in 94% of its nylon-based accessories since 2021 — resulting in a verified 63% reduction in nylon-related emissions per unit compared to 2019 baselines (Stella McCartney Impact Report 2023, p. 14).
Leather: Traceability as the Linchpin
Leather remains central to luxury accessories — accounting for 61% of handbag material value (Statista, 2023). Yet traceability lags dramatically. Only 3.2% of global luxury leather supply chains are fully traceable to farm level (Kering Materials Innovation Lab, 2023). Kering’s Open Source platform — launched in 2020 — now covers 78% of its direct leather suppliers, requiring GPS-tagged farm locations, deforestation risk scores (via Global Forest Watch), and monthly tannery wastewater pH and chromium-III/VI readings. As of Q1 2024, 54% of Kering’s leather met its Tier 1 traceability standard (full chain from farm to tannery); LVMH reported 29% for its Louis Vuitton and Celine lines in the same period.
Without traceability, sustainability claims collapse. A 2022 investigation by the Changing Markets Foundation found that 62% of ‘Amazon-safe’ leather bags sold by European retailers contained hides sourced from farms operating within 10 km of documented deforestation hotspots in Mato Grosso, Brazil — despite brand-level commitments to zero-deforestation supply chains.
Water, Waste, and the Hidden Cost of Craftsmanship
Handbag manufacturing consumes staggering volumes of water — especially in dyeing, finishing, and leather tanning. Conventional chrome tanning uses 35–50 liters of water per square meter of hide; vegetable tanning requires 60–80 liters but extends processing time by 3–6 weeks and increases cost by 220%. Kering’s 2023 Water Program reduced average water use per leather unit by 31% across its Tier 1 tanneries — from 42 L/m² to 29 L/m² — through closed-loop rinse systems and enzymatic pre-treatments. Yet this represents only 18% of Kering’s total water footprint; upstream feedlot irrigation and hide transport remain largely unmonitored.
Waste is equally opaque. Luxury handbag production generates 12–18% material waste by volume due to pattern cutting inefficiencies. At Hermès’ Pantin workshop, artisans achieve <7% leather waste through master pattern optimization and offcut repurposing — but this craftsmanship-intensive model scales poorly. Coach’s automated nesting software reduced cut-waste by 14% between 2021–2023, yet still operates at 10.3% average waste. Meanwhile, small-batch brands like Matt & Nat report 99.4% material utilization via digital pattern stacking and zero-waste design protocols — though their 2023 production volume (127,000 units) is less than 0.7% of Coach’s annual output (18.2 million units, Coach FY2023 Annual Report).
Repair, Resale, and the Second-Life Imperative
True sustainability requires decoupling value creation from virgin resource extraction. Resale revenue in accessories grew 22% YoY in 2023 (ThredUp Resale Report), yet brand-controlled resale programs remain limited. Chanel launched its ‘Reef’ pre-owned authentication service in 2022, processing 24,000 handbags in Year 1 — representing just 0.08% of its estimated 30 million handbags sold since 2000. By comparison, The RealReal authenticated and resold 412,000 luxury handbags in 2023 — 72% of which were Chanel, Louis Vuitton, or Gucci — indicating robust secondary demand the brands themselves aren’t capturing.
Repair infrastructure is even thinner. Of the top 15 global accessories brands, only 4 (Patagonia, Stella McCartney, Mulberry, and Veja) offer free lifetime repair guarantees with published turnaround times and spare-part inventories. Mulberry’s ‘Rejuvenate’ program repaired 14,200 handbags in 2023 — extending average product life by 4.2 years — yet accounts for just 1.3% of its annual sales volume. Most brands charge €120–€380 for basic strap replacement or hardware refurbishment, discouraging repair in favor of replacement.
Transparency Benchmarks: Who’s Publishing What?
Public disclosure remains the strongest predictor of actual performance. The Fashion Transparency Index 2023 scored 250 brands on policy, governance, traceability, supplier assessment, and remediation. In accessories, the highest-scoring brands were:
| Brand | Overall Score (out of 100) | Traceability to Tier 1 | Public Emission Data (Scope 1–3) | Living Wage Commitment |
|---|---|---|---|---|
| Patagonia | 89 | 100% | Yes (2022: 129,400 tCO₂e) | Yes (audited in 82% of Tier 1) |
| Stella McCartney | 78 | 94% | Yes (2023: 51,200 tCO₂e) | No formal commitment |
| Kering Group | 71 | 78% (direct suppliers) | Yes (2022: 214,000 tCO₂e) | Yes (2025 target) |
| LVMH | 44 | 29% (direct suppliers) | Scope 1&2 only | No public commitment |
| Coach (Tapestry) | 36 | 42% (leather only) | Scope 1&2 only | No public commitment |
Note: 'Traceability to Tier 1' means verified facility names, addresses, and production volumes — not just country-level sourcing. LVMH’s score dropped 9 points from 2022 due to discontinued publication of tannery audit summaries. Tapestry’s 36 reflects improved chemical management reporting but persistent gaps in raw material origin disclosure.
The Cost of Doing Good: Pricing, Margins, and Consumer Realities
Sustainable production carries quantifiable cost premiums — but these vary widely by intervention. According to the Sustainable Apparel Coalition’s 2023 Costing Tool, verified organic cotton adds 18–22% to fabric cost; LWG Gold-certified leather adds 12–15%; GRS-certified recycled nylon adds 9–11%. However, labor cost premiums dominate: paying living wages (as defined by Wage Indicator Foundation) adds 27–33% to base manufacturing costs in Vietnam and Bangladesh — where 61% of non-luxury accessories are assembled.
Brands absorb or pass on these costs differently. Patagonia prices its recycled nylon backpacks 14% above comparable virgin-nylon models — citing full cost accounting. Stella McCartney maintains parity pricing across most lines, absorbing ~8% margin compression through vertical integration and R&D amortization. Conversely, Michael Kors’ 2023 ‘Conscious Collection’ carried identical MSRPs to core products — implying no cost pass-through, raising questions about scale of sustainable inputs used (only 23% of collection materials were certified recycled or organic, per its 2023 ESG supplement).
Consumer willingness-to-pay remains constrained. A 2023 YouGov survey of 12,000 U.S. and EU shoppers found that 64% would pay ≤5% more for verified sustainable accessories; only 12% would pay ≥15% more. This creates structural tension: brands needing margin protection versus sustainability initiatives requiring investment.
Investor Pressure and Regulatory Shifts
Regulatory mandates are accelerating accountability. The EU Corporate Sustainability Reporting Directive (CSRD), effective January 2024, requires all large companies operating in the EU — including U.S.-based Tapestry and Capri Holdings — to disclose double-materiality assessments, climate transition plans, and supply chain due diligence aligned with the OECD Due Diligence Guidance. Non-compliance risks fines up to 10% of global turnover.
Investors are acting: In 2023, 73% of S&P Global LargeCap firms faced at least one ESG-related shareholder proposal — up from 41% in 2019. The $4.1 trillion California Public Employees’ Retirement System (CalPERS) filed resolutions demanding full Scope 3 disclosure from Kering and LVMH, citing portfolio risk exposure to biodiversity loss and water stress.
Beyond the Buzzword: What Meaningful Progress Looks Like
Progress isn’t defined by aspirational targets alone — it’s measured in audited reductions, enforced standards, and structural shifts. Three brands exemplify actionable models:
- Patagonia’s Worn Wear Ecosystem: Operates 5 regional repair hubs, stocks 2,100+ spare parts, and offers free shipping for repairs. In 2023, it refurbished 127,000 items — diverting 142 metric tons of textile waste. Its ‘Don’t Buy This Jacket’ campaign drove a 30% YoY increase in repair sign-ups, proving ethics can drive engagement without greenwashing.
- Kering’s Materials Innovation Lab: Since 2019, invested €120M in bio-based alternatives — including Mylo™ mycelium leather (used in Stella McCartney’s 2022 Falabella bag) and grape-skin leather (Vegea™). Lab-scale production achieved 89% lower water use and 76% lower CO₂e than bovine leather — though commercial scaling remains at <0.02% of Kering’s total leather volume.
- Mulberry’s ‘Radical Transparency’ Dashboard: Launched in 2023, publishes real-time data on energy use per bag (kWh), water per unit (L), and leather origin maps — updated quarterly. It revealed that its Somerset factory uses 28% less grid electricity than industry average, validating on-site solar investments.
These efforts share three traits: they’re auditable, they quantify trade-offs (e.g., Mylo’s lower impact but higher cost and limited durability), and they integrate sustainability into P&L accountability — not just CSR reporting.
Consumers and investors must shift focus from ‘Is this brand sustainable?’ to ‘What specific, verified actions has this brand taken — and what data proves it?’ A ‘sustainable’ label means little without kilowatt-hours saved, liters of wastewater treated, or percentage of suppliers paying living wages. Brands that treat sustainability as a compliance exercise will fall behind; those embedding it into procurement, design, and finance — with transparent, third-party-verified metrics — are building resilience, trust, and longevity. The future belongs not to the greenest claim, but to the most rigorously measured action.
For accessories buyers, this means asking sharper questions: Is the recycled nylon certified to GRS v4.1? Does the leather tannery publish monthly chromium-VI test results? Are repair parts available for >5 years? These aren’t niche concerns — they’re the baseline for responsible consumption in a resource-constrained world.
The divide between sustainability and brands isn’t philosophical — it’s operational. Closing it requires replacing narrative with numbers, ambition with audit, and aspiration with accountability. That work is underway — unevenly, imperfectly, but undeniably.
When Kering reduced water use by 31% per leather unit, it didn’t rely on a new slogan. It installed flow meters, trained tannery technicians in enzymatic pretreatment, and mandated quarterly wastewater testing. That’s the work that matters — not the headline, but the hectoliter saved, the gram of chromium prevented, the artisan retrained in zero-waste cutting.
Brands that master this granular, grounded approach won’t just meet regulatory thresholds — they’ll redefine luxury itself: not as scarcity of material, but as abundance of integrity.
Transparency isn’t a marketing tactic. It’s the infrastructure of trust. And in accessories — where a single handbag represents 40+ hours of skilled labor and 200+ material inputs — trust must be earned, one verified metric at a time.
The most powerful sustainability statement a brand can make isn’t printed on a hangtag. It’s embedded in a repair log, a tannery audit report, or a publicly shared Scope 3 inventory. That’s where the real work lives — and where the future of responsible accessories is being built.
Consumers hold leverage not through boycotts alone, but through precise, informed demand: for data, not declarations; for repairability, not recyclability; for traceability, not terminology. When shoppers ask for the chromium test report before purchasing a leather tote, they’re not being difficult — they’re enforcing accountability.
That shift — from passive recipient of brand storytelling to active verifier of impact — is the quiet revolution transforming the accessories industry. It’s happening in spreadsheets, lab reports, and factory audits — not press releases. And it’s already changing what ‘quality’ means.